News
OverDrive Logistics Market Report – August 24, 2026

Tony Broyles
August 24, 2026
Truckload Capacity Remains Tight Despite Softer Freight Demand
This remains the most important story in the freight market.
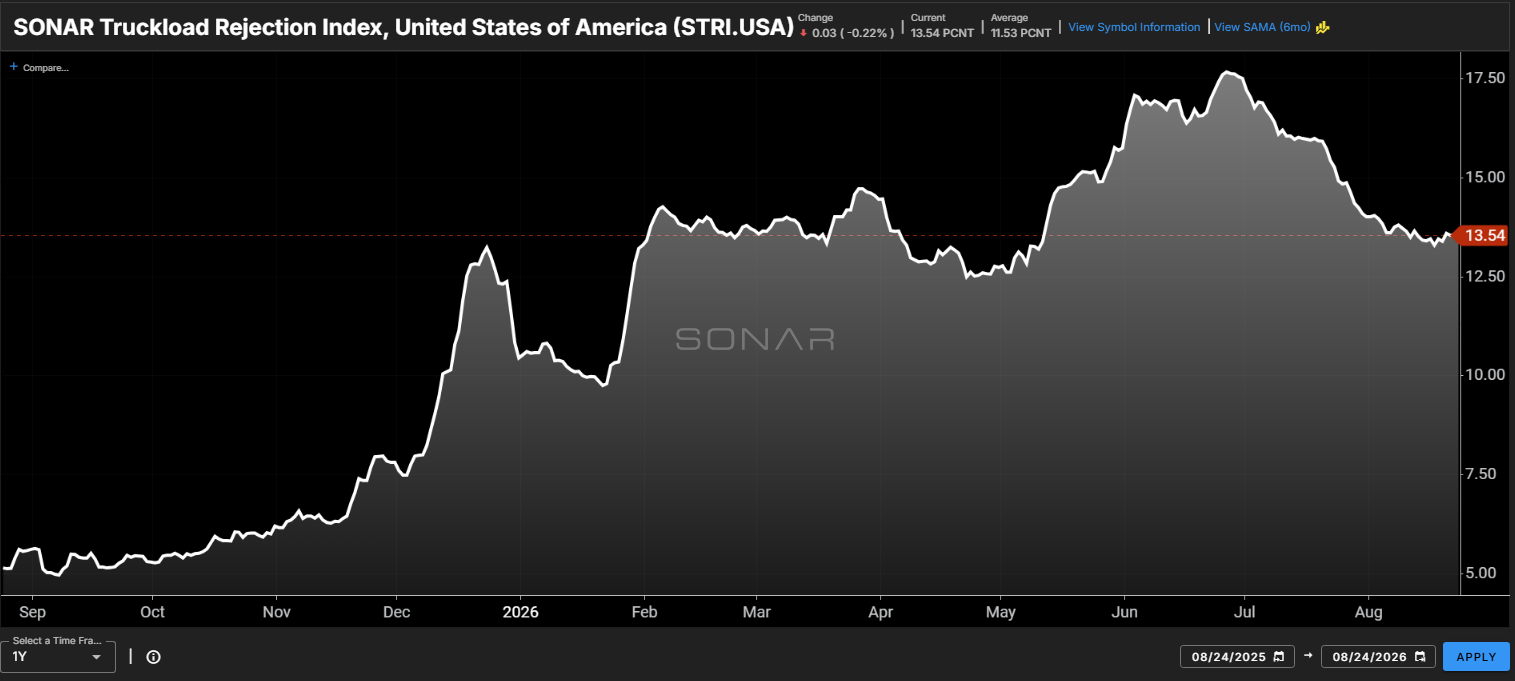
National truckload demand has softened somewhat during August, but available capacity remains constrained. Tender rejection rates continue to run well above levels generally associated with a balanced truckload market, while transportation capacity contracted sharply during July.
The key issue is that rates are increasingly being driven by truck supply rather than exceptionally strong freight demand. The market simply has fewer trucks available to absorb increases in volume.
Diesel Prices Are Adding Significant Cost Pressure
Fuel has re-emerged as one of the largest transportation-cost concerns.
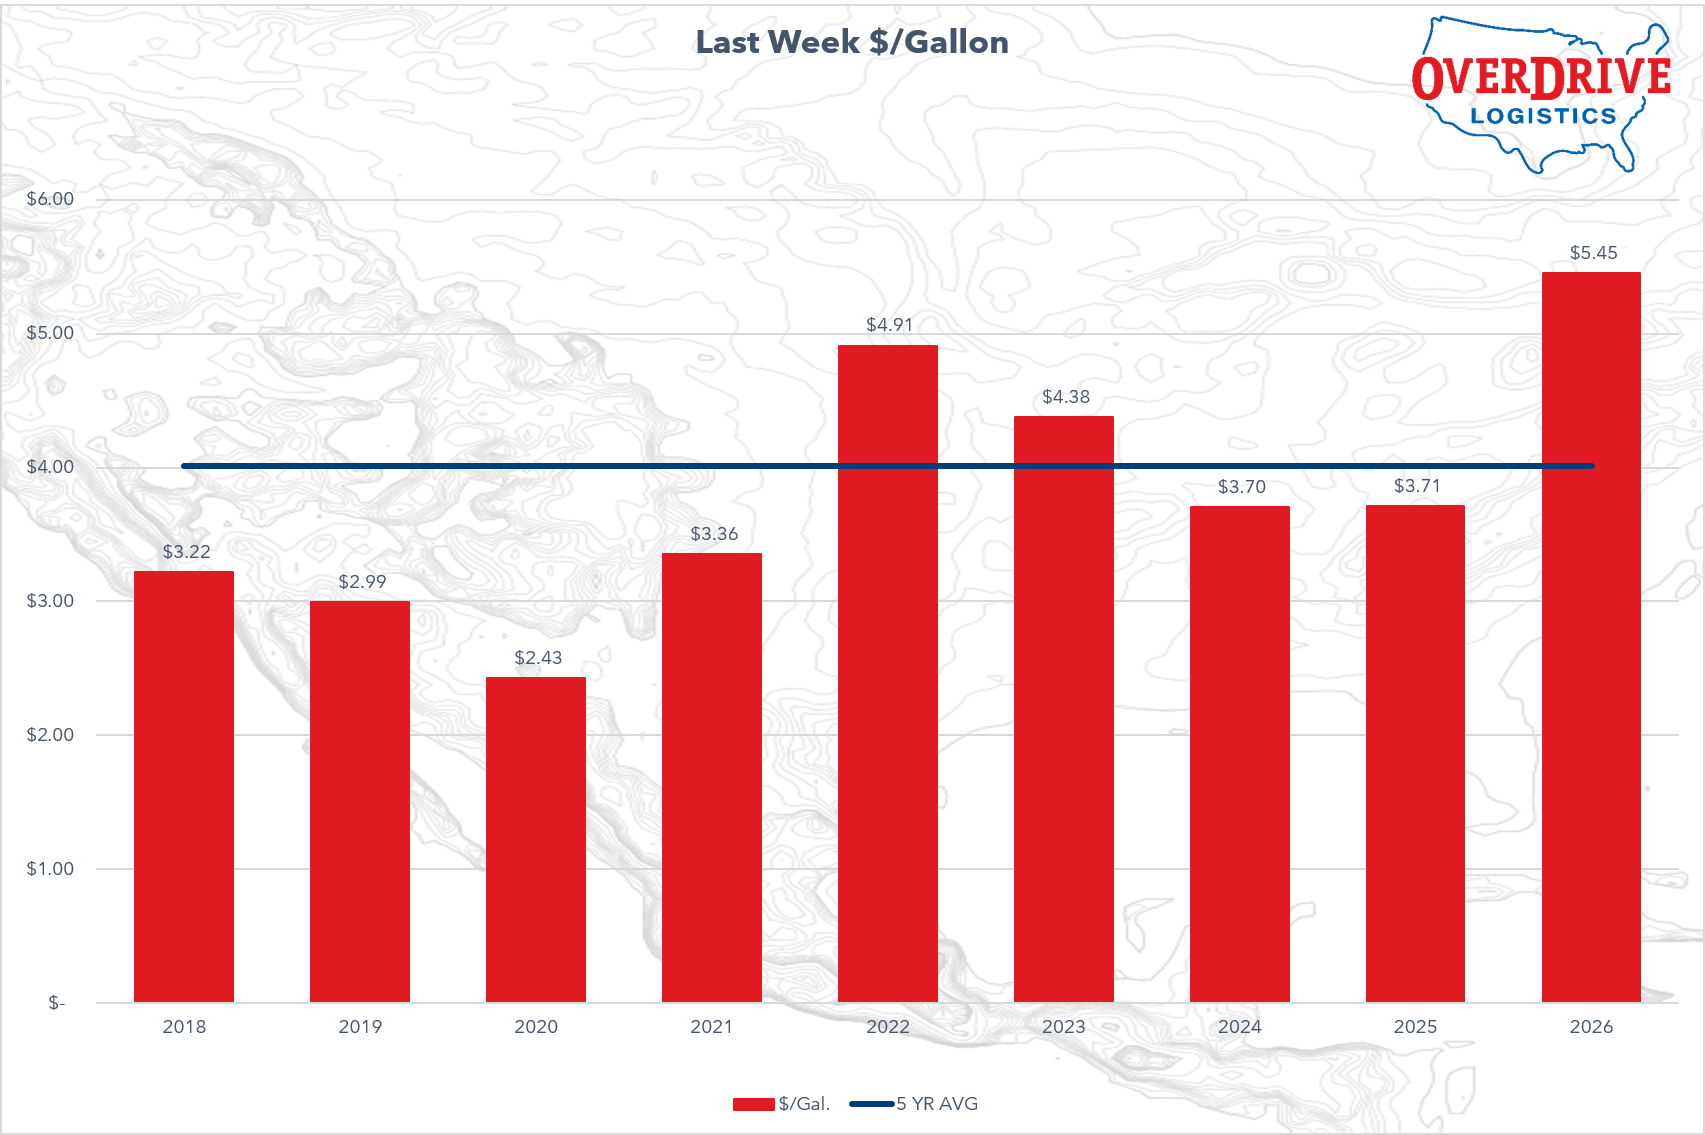
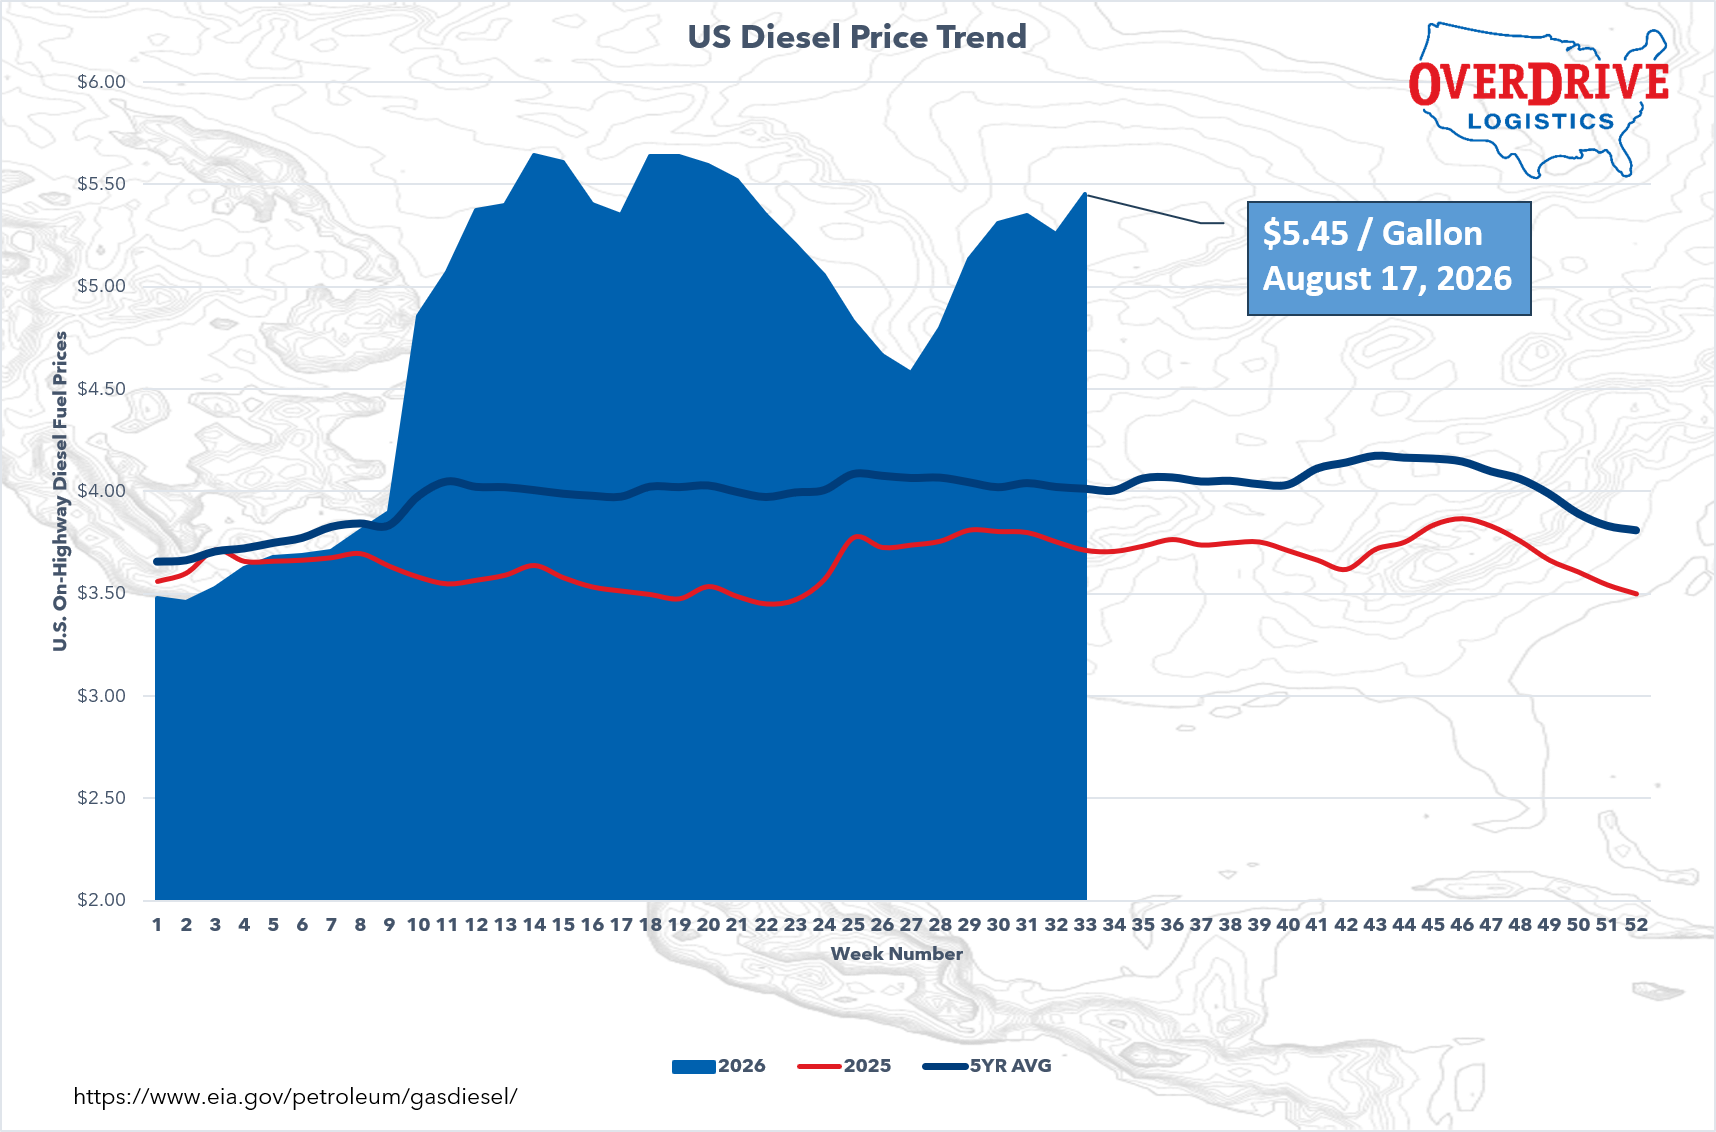
National diesel reached approximately $5.45 per gallon in mid-August, up roughly 88 cents per gallon in only six weeks. That increase is affecting transportation costs even on lanes where base linehaul rates have remained relatively stable.
For shippers using fuel-surcharge programs, the impact can quickly add hundreds of dollars to a long-haul shipment.
Shippers Are Tendering Freight Earlier to Protect Capacity
Truckload tender lead times recently reached approximately 3.7 days, their highest level in at least three years.
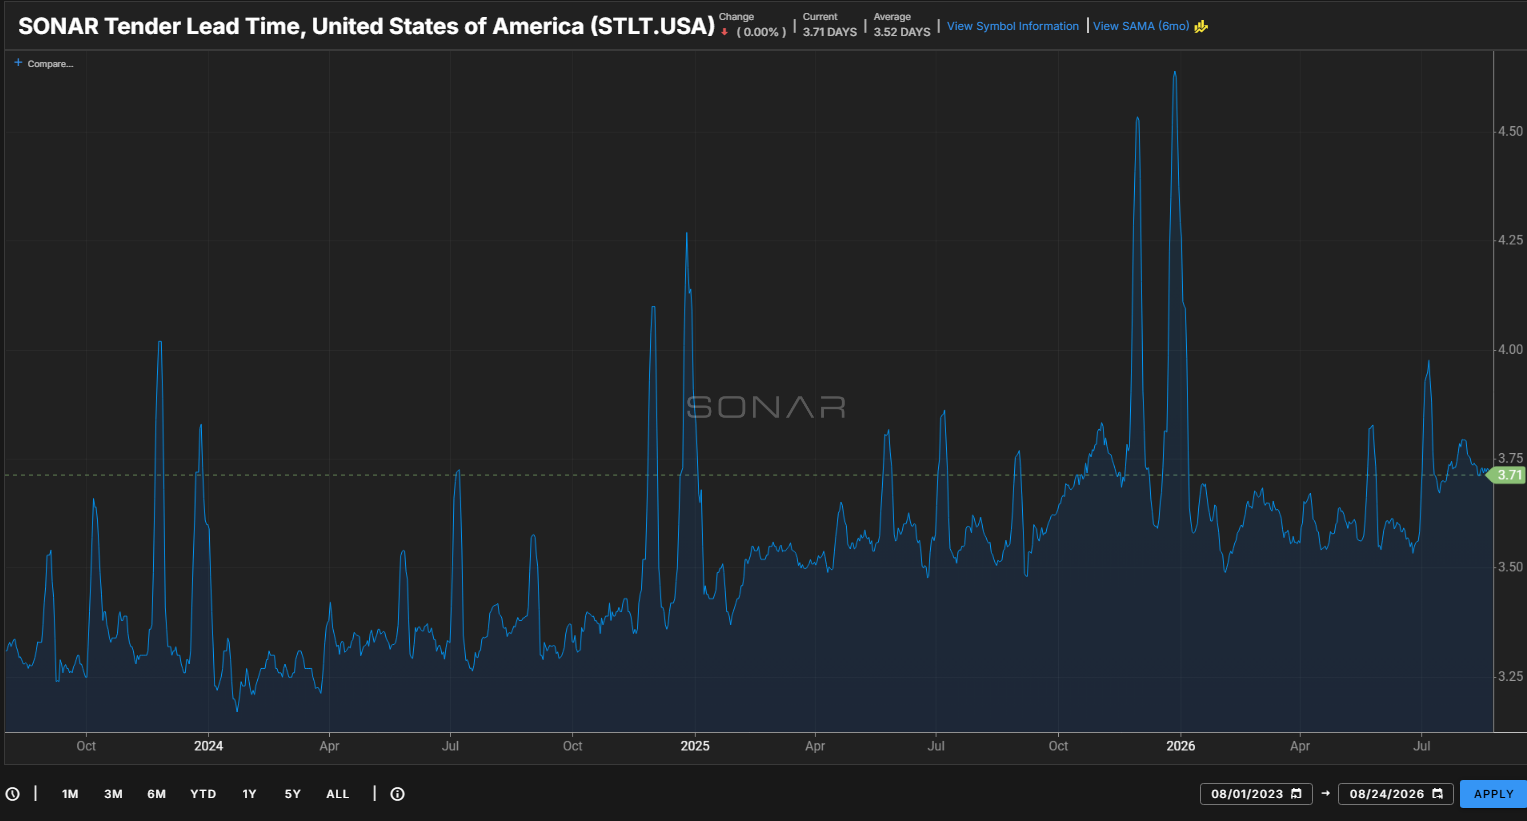
This is an important market signal. Shippers are recognizing that waiting until the day before pickup significantly reduces available carrier options.
Providing additional lead time allows carriers and brokers to:
- Position equipment more efficiently
- Match freight with backhaul opportunities
- Access a larger pool of qualified carriers
- Avoid expensive last-minute spot-market purchases
Intermodal Is Becoming a More Attractive Alternative to Truckload
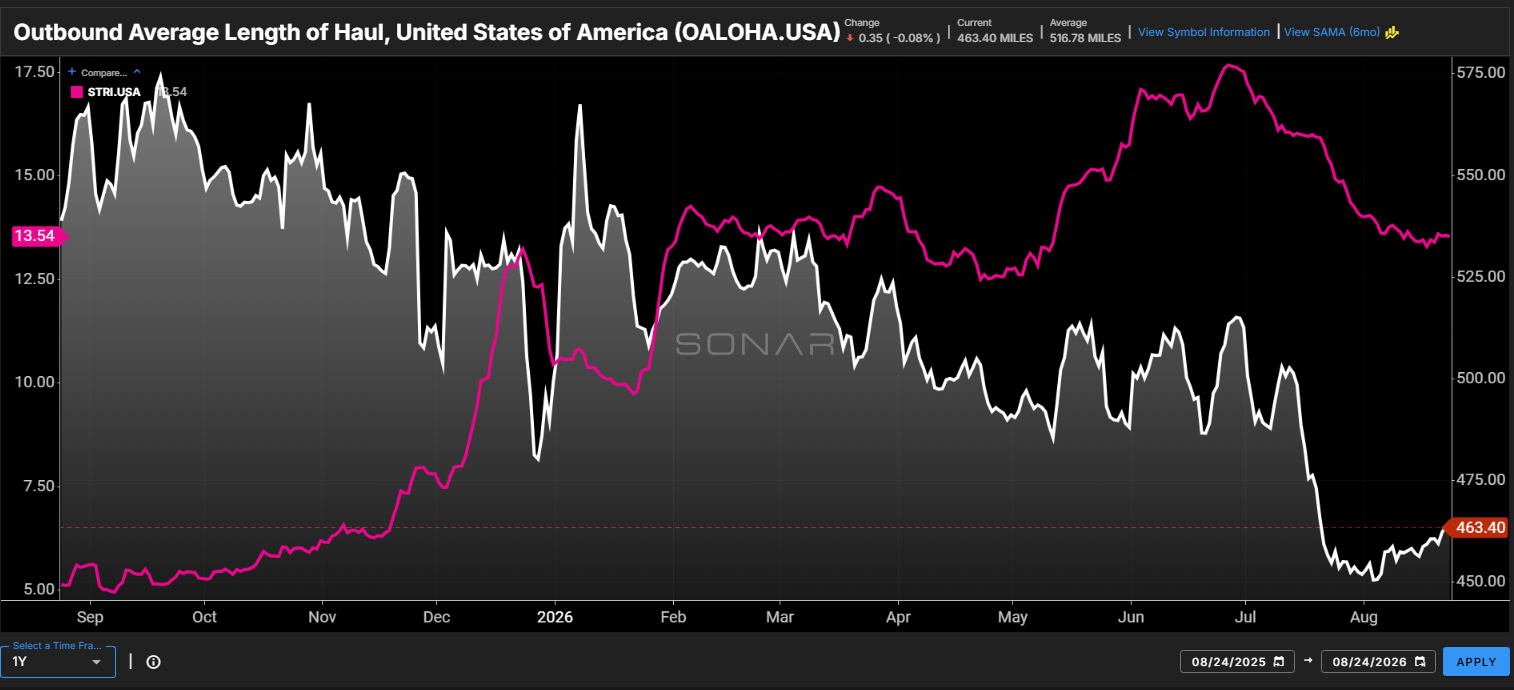
Higher truckload pricing is widening the gap between over-the-road and intermodal transportation. And as truckload rates have increased and truckload capacity has decreased, long-haul OTR shipments have fallen off a cliff. According to SONAR (chart below), the average length of haul fell from just over 500 miles to 463 as of August 24th. Long-haul freight hasn’t disappeared, more of it is moving on the rail via intermodal shipping.
On certain long-haul lanes, industry data indicate that intermodal savings can reach 30%–50% compared with truckload, depending on the lane, transit requirements and available rail service.
Intermodal is particularly worth evaluating for:
- Freight moving 700+ miles
- Consistent origin/destination pairs
- Predictable weekly volume
- Non-expedited shipments
- Freight with flexible transit requirements
Freight Fraud and Cargo Theft Remain Major Risks
Carrier selection has become just as important as carrier pricing.
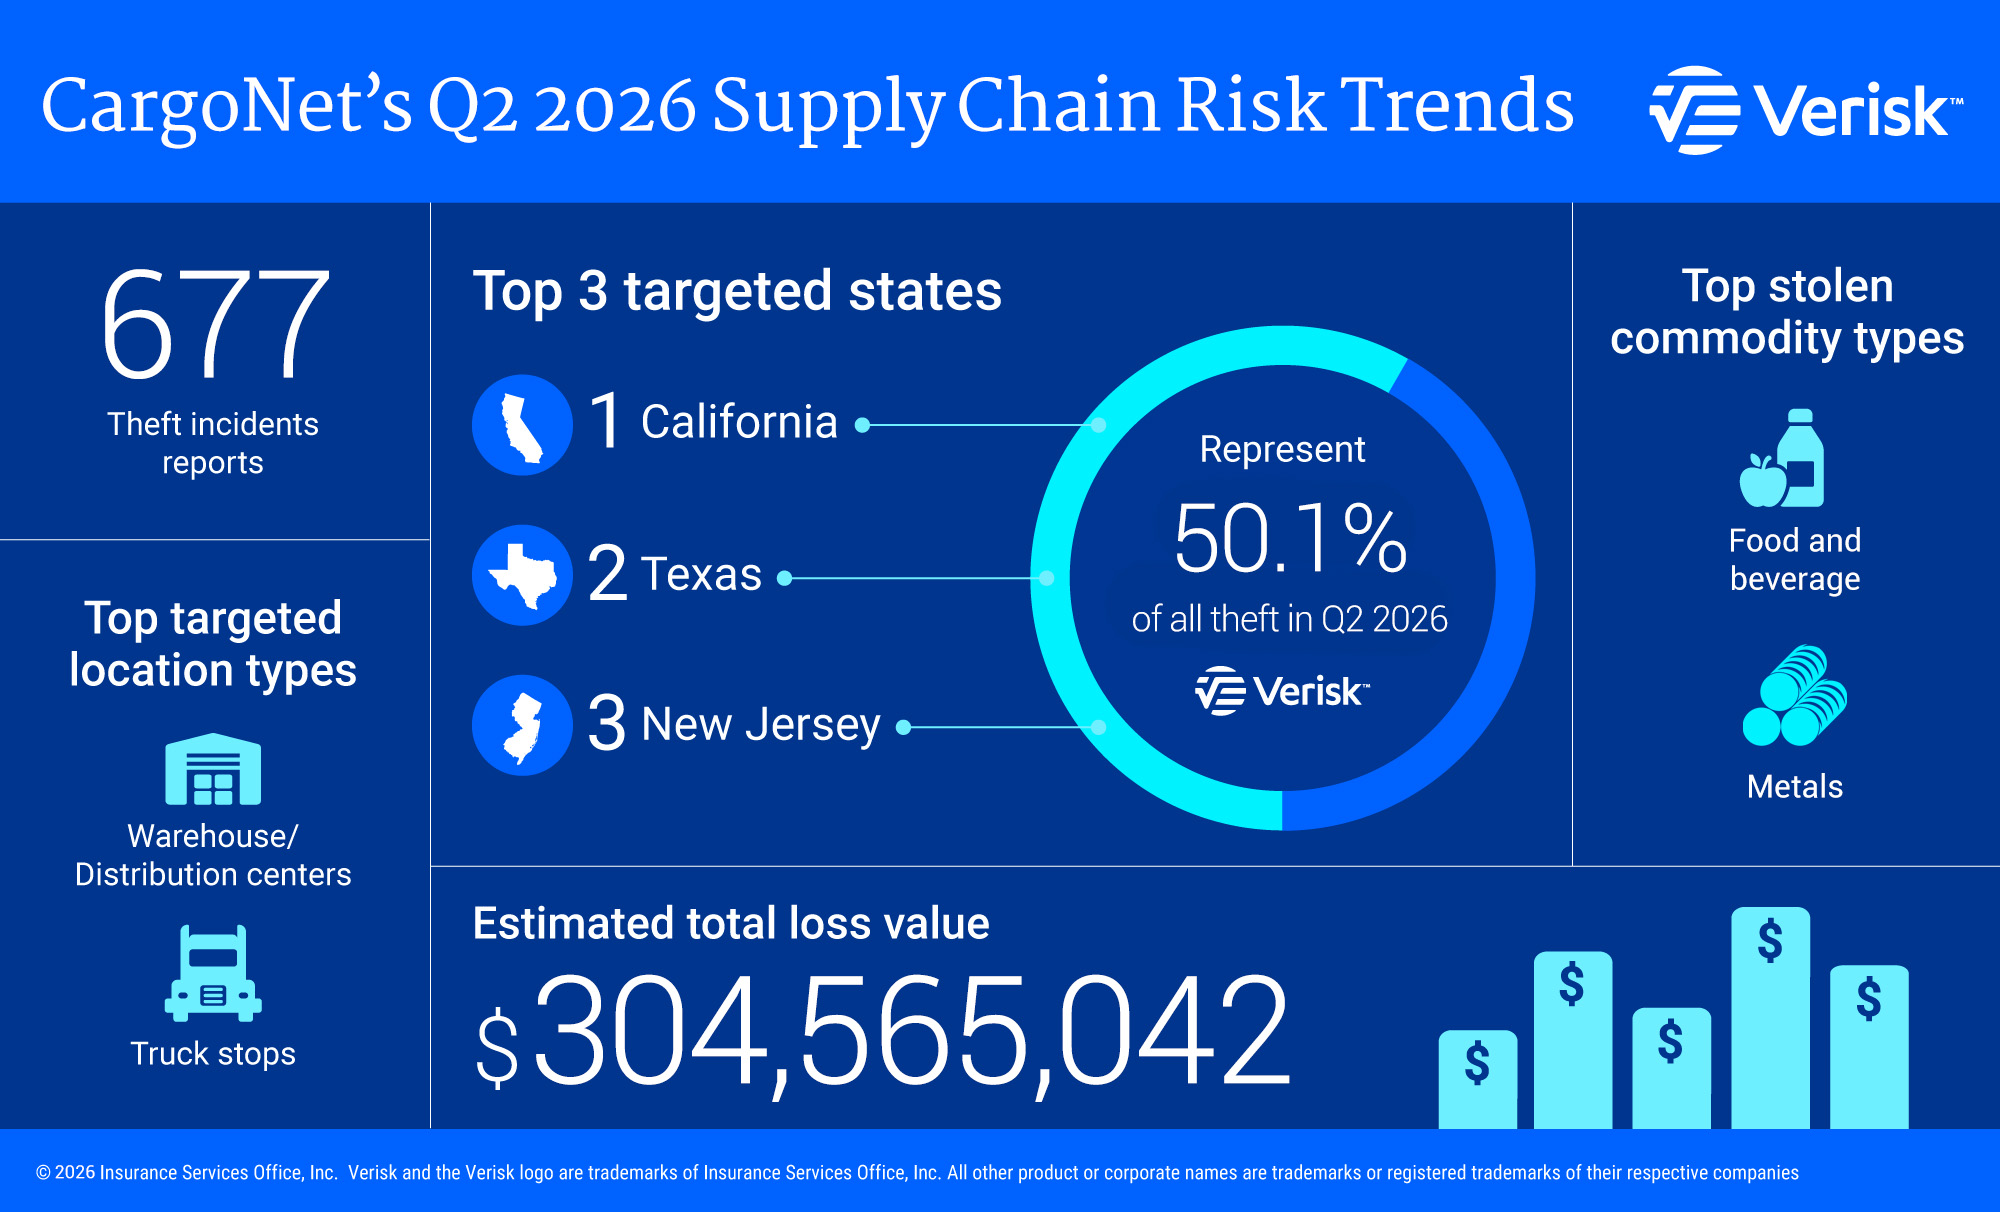
CargoNet reported 677 cargo-theft incidents during Q2, with estimated losses totaling approximately $305 million. The average reported shipment value was roughly $564,000.
Criminal schemes increasingly involve:
- Carrier impersonation
- Fraudulent MC numbers
- Double brokering
- Shipment rerouting
- Identity theft
- Falsified insurance and carrier documents
The growth of new carrier authorities also makes vetting more complicated because many newly registered carriers have limited inspection, safety and operating histories.
What shippers should do now
The current market favors companies that plan rather than react.
▶️Tender earlier.
▶️Benchmark lanes individually.
▶️Watch fuel costs.
▶️Evaluate intermodal opportunities.
▶️And make carrier quality and verification part of every transportation decision.
How OverDrive Logistics Can Help
At OverDrive Logistics, our goal is not simply to find the cheapest available truck. We work to identify the best combination of price, service and carrier quality for every shipment.
Our team helps shippers:
- Benchmark freight rates against current market conditions
- Secure dependable capacity on difficult lanes
- Identify opportunities for truckload, reefer, flatbed, LTL and intermodal alternatives
- Thoroughly vet carriers before freight is tendered
- Monitor shipments and proactively manage exceptions
- Use market intelligence to determine where to negotiate aggressively and where capacity should be protected
The freight market is changing quickly. Shippers that understand those changes and make transportation decisions proactively will be better positioned to maintain service while controlling freight costs.
What we’re watching next
As we move toward September, the biggest indicators to watch are truckload tender rejections, diesel prices, additional carrier exits, late-summer produce movements, and early fall retail and manufacturing demand. If freight demand increases even modestly while capacity continues to contract, shippers could see another round of rate pressure heading into Q4.
Prepared by OverDrive Logistics for customer education and market awareness.
Source references include FreightWaves, EIA, SONAR, CargoNet and industry reporting.